akshare
AKShare is an elegant and simple financial data interface library for Python, built for human beings! 开源财经数据接口库
- 23k
- Python
- MIT
- 16 h ago
Additional linear models including instrumental variable and panel data models that are missing from statsmodels.
Repo bashtage/linearmodels, read from GitHub 10 min ago. bashtage has not joined Take My Repo.
bashtage/linearmodels is a public repo on GitHub by bashtage. Additional linear models including instrumental variable and panel data models that are missing from statsmodels. It declares the NCSA license on GitHub. It is written mainly in Python, has 1,080 stars and last changed on 2026-11-11. Nobody has reviewed it on Take My Repo yet, which says nothing about its quality. Read from GitHub on 2026-11-21.
GitHub is limiting requests or did not answer. The facts on this page still come from the last successful read.
Open on GitHubbashtage/linearmodels is a public repo on GitHub by bashtage. Additional linear models including instrumental variable and panel data models that are missing from statsmodels.
It declares the NCSA license on GitHub.
Its maker has not tagged a system, so it is unknown here. Its README says what it needs.
Open "Take it" on its page: Take My Repo writes an install plan for your machine and hands it to your AI agent (Claude Code, Codex or Cursor), which asks you before each step. Take My Repo has not tested it on any machine.
Its last change on GitHub was on 2026-11-11. Take My Repo does not judge from that whether it is maintained.
Nobody has reviewed it on Take My Repo yet, which says nothing about its quality.
AKShare is an elegant and simple financial data interface library for Python, built for human beings! 开源财经数据接口库
Notebooks for financial economics. Keywords: Jupyter notebook pandas Federal Reserve FRED Ferbus GDP CPI PCE inflation unemployment wage income debt Case-Shiller housing asset portfolio equities SPX bonds TIPS rates currency FX euro EUR USD JPY yen XAU gold Brent WTI oil Holt-Winters time-series forecasting statistics econometrics
Tools for financial economics. Curated wrapper over Python ecosystem. Source code for fecon235 Jupyter notebooks.
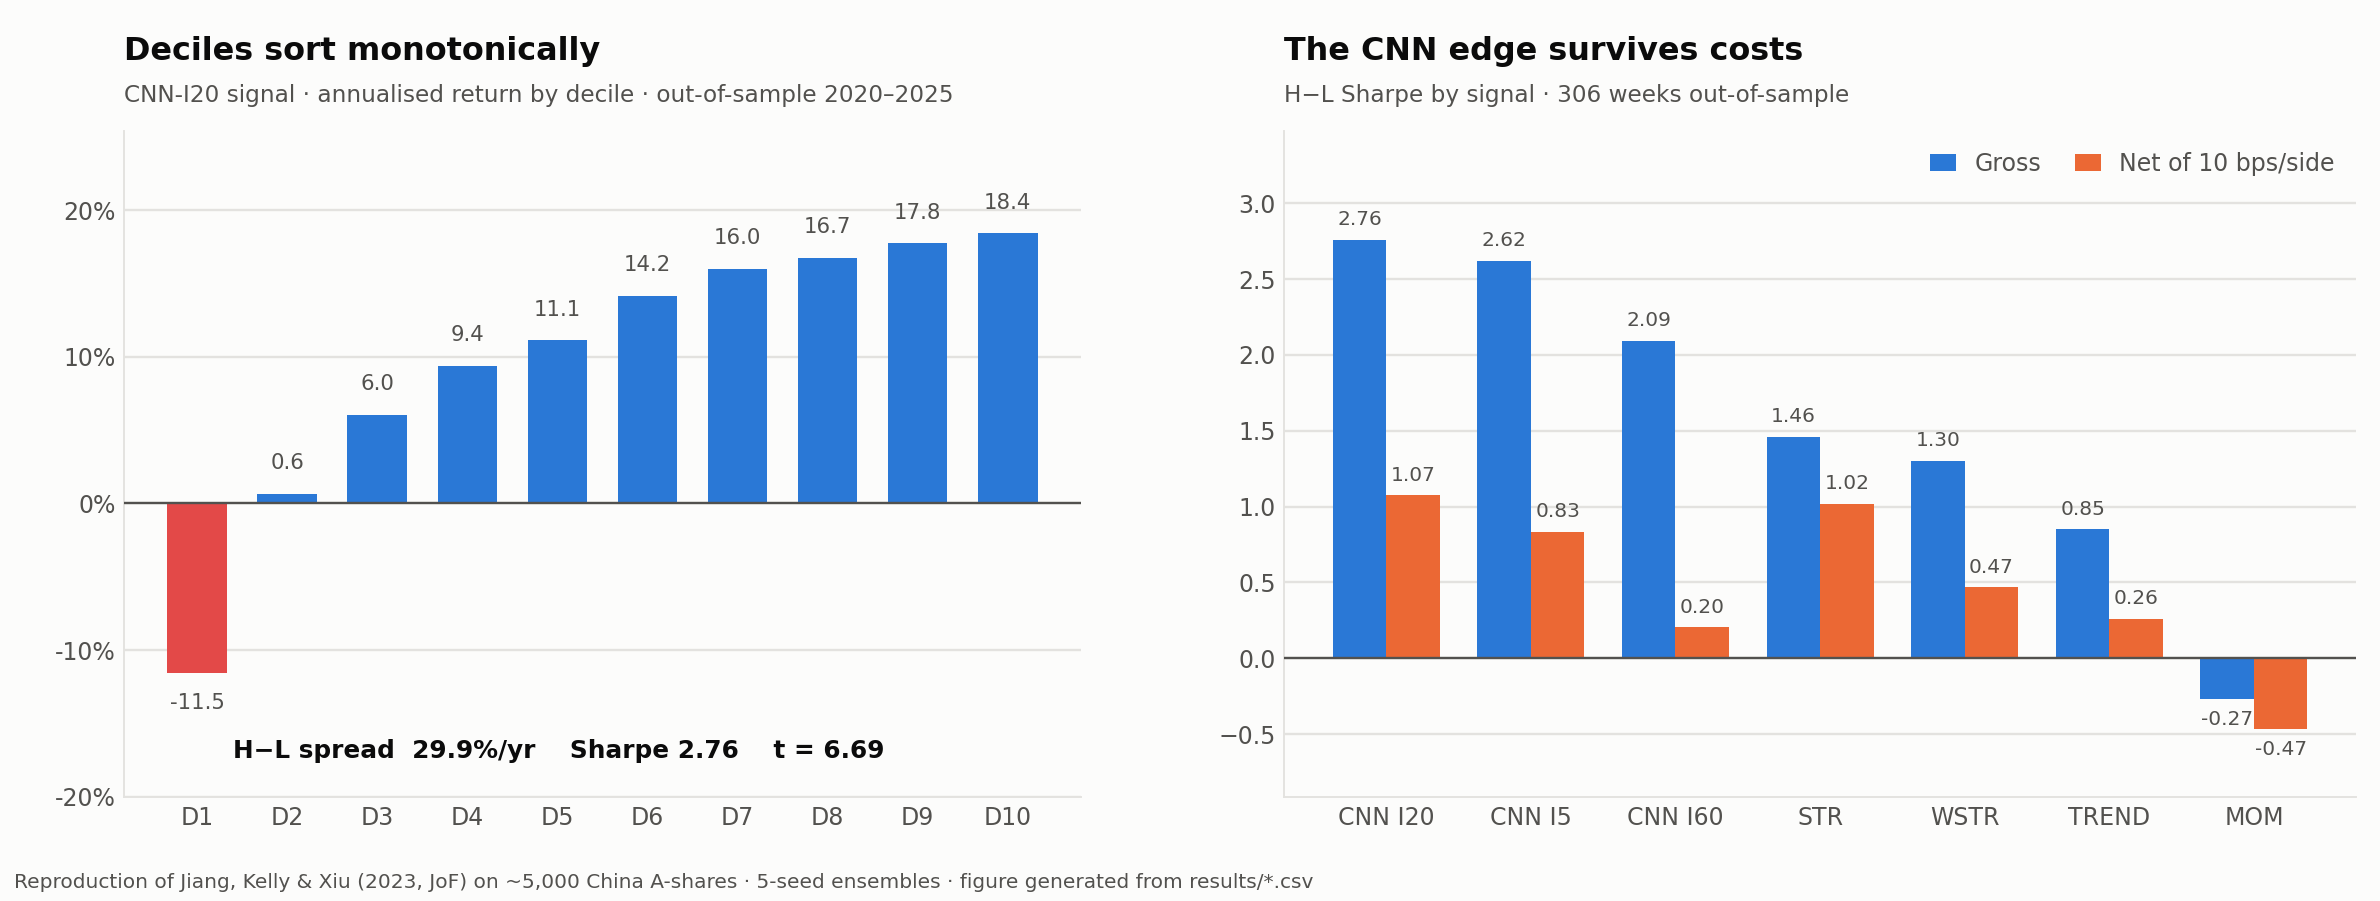
Reproducing the Journal of Finance image-based CNN momentum strategy on ~5,000 China A-shares — H−L Sharpe 2.76 gross / 1.07 net, out-of-sample 2020–2025
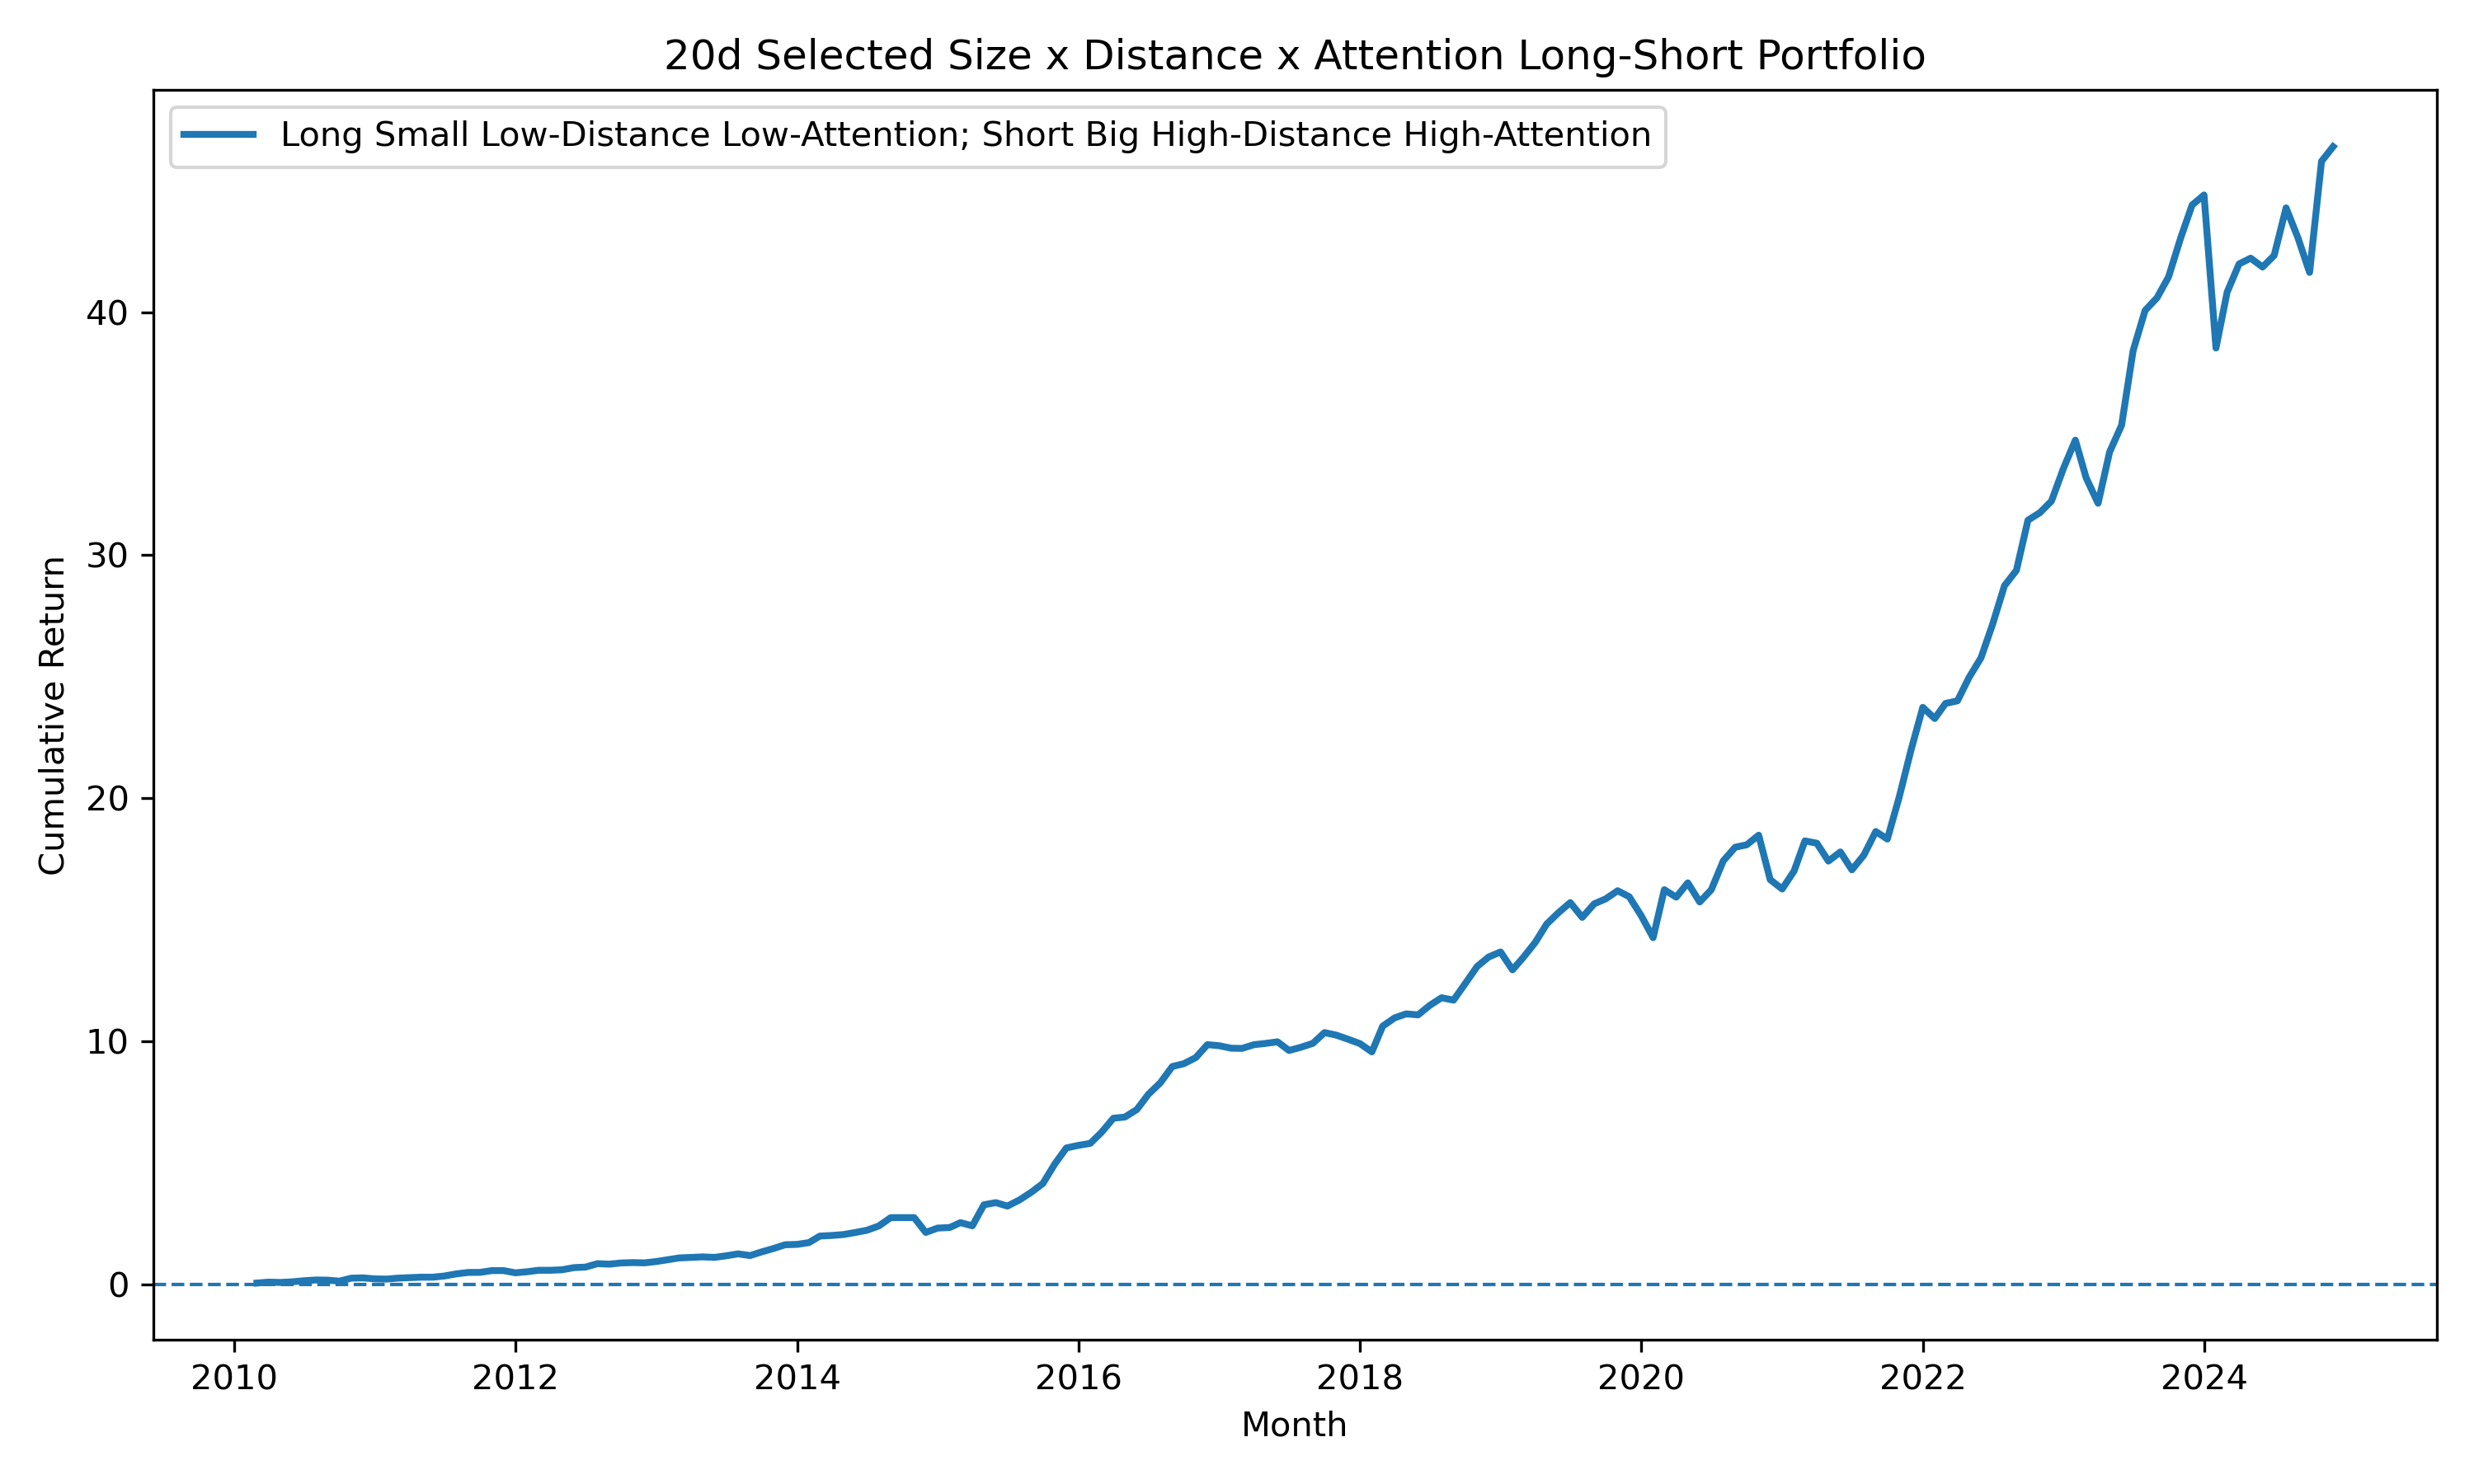
Empirical China A-share volatility-sensitivity factor research with portfolio sorting, robustness tests, sentiment and attention extensions, and a reproducible synthetic demo.
Asset-pricing and macro research platform with pricing experiments, evidence-quality diagnostics and research workflow orchestration.
Numpy-compatible bit generators and add some random variate distributions missing from NumPy.
A set of notebooks the provide an introduction to Python.
Code from "Introduction to Python for Econometrics, Statistics and Data Analysis" by Kevin Sheppard