agh-quantitative-measures-of-market-risk
This repository consits of: projects and homeworks connected with research area such as Risk Management.
- 5
- Jupyter Notebook
- MIT
- 2 y ago
This repository consits of: projects and homeworks connected with research area such as Risk Management.
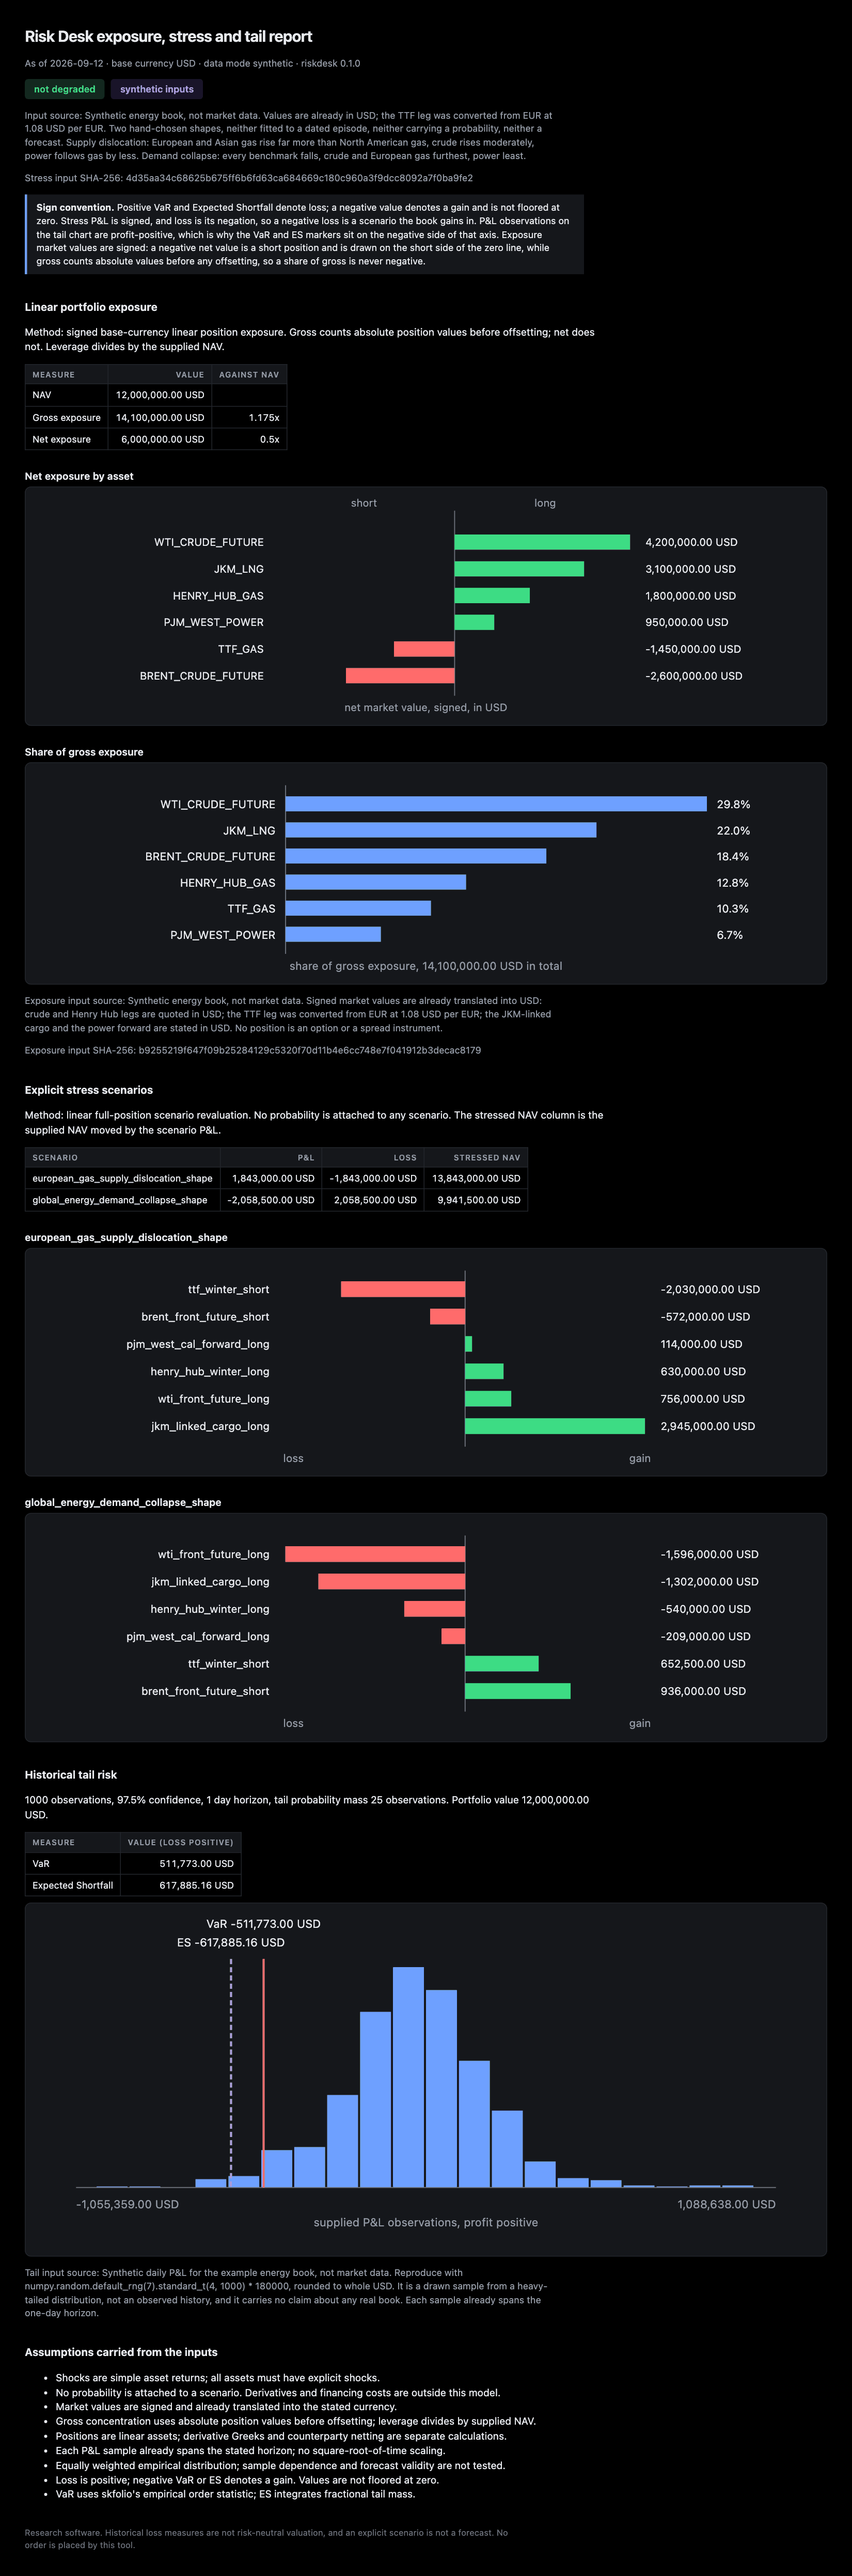
Portfolio risk an AI agent can drive and a person can read. Historical VaR and Expected Shortfall, signed linear exposure, explicit stress scenarios, counterparty exposure and XVA through a local ORE project. 4 MCP tools, 5 skills, a local dashboard and a hosted service. Research software, not investment advice. Noncommercial licence.
MPT in Python | Efficient Frontier modeling, Fama French 3 Factor Analysis, Monte Carlo Simulations and Portfolio Risk Analysis (Sharpe, VaR)
Question answering model, used with economics-finance-ai999x.
Zero-dependency quantitative-finance toolkit in pure TypeScript: VaR/CVaR, Black-Scholes + Greeks, bond duration, risk parity. No dependencies. (TS sibling of the Python purequant)
Zero-dependency quantitative-finance toolkit in pure Python: VaR/CVaR, Black-Scholes + Greeks, bond duration, risk parity, factors, backtests. No numpy/pandas.
Multi-Equipment CBM system using QR-DQN with advanced probability distribution analysis. Coordinated maintenance decision-making for 4 industrial equipment units with realistic anomaly rates (1.9-2.2%), comprehensive risk analysis (VaR/CVaR), and 51-quantile distribution visualization.